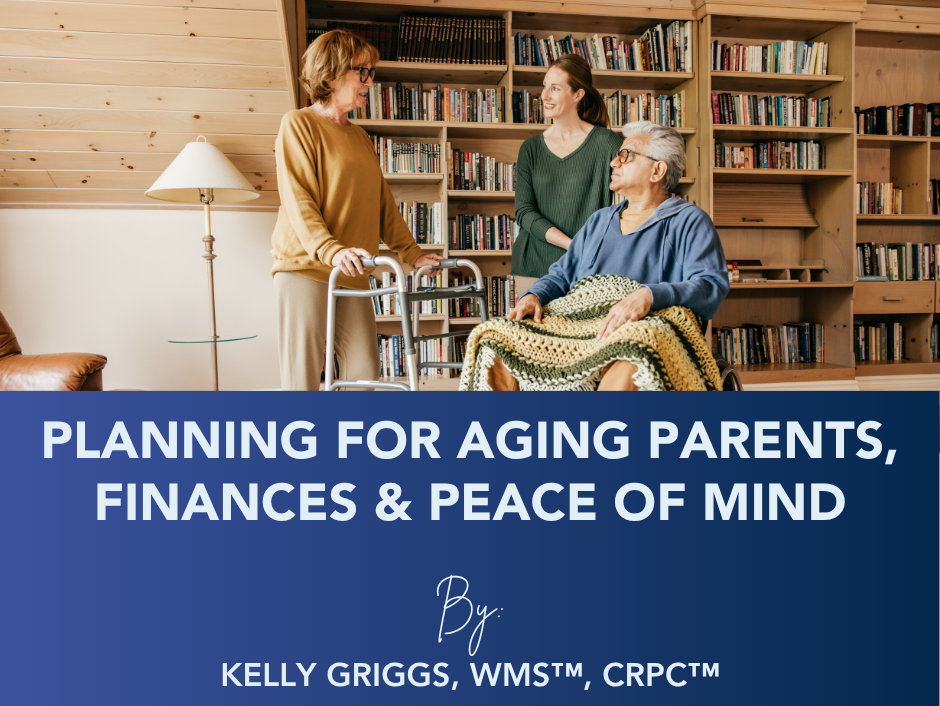
In my previous article, “Caring for an Aging Parent,” we explored how to begin conversations with aging loved ones about their future healthcare needs. In this Part II, we’re diving into the
why—why long-term care (LTC) planning is so critical for families today.
Let’s start with some hard truths:
- 7 out of 10 people over age 65 will require some form of long-term care support.
- 66% of caregivers tap into their own retirement or savings to cover the cost of care for a loved one.
- 100% of families are impacted in some way.
The importance of this topic becomes immediately clear:
LTC will likely affect every single person reading this. It might be your parents who need care. It could be your spouse’s parents. And, statistically speaking,
you or your spouse are very likely to need support in the future.
In our financial planning practice, it’s our responsibility to address topics that can dramatically affect the outcome of decades of hard-earned savings. The good news is, there are many strategies and tools available today that can help you prepare and protect your family’s financial future.
What Are Your Options?
1. Traditional Long-Term Care Policies
Standalone LTC policies were widely used 30 years ago, but many providers have since exited the market or increased premiums to unsustainable levels due to rising life expectancy. For that reason, we do not recommend these policies and won’t spend time reviewing them here.
2. Life Insurance with Long-Term Care Benefits
For older clients, we often recommend life insurance policies that provide LTC coverage if needed—but also offer a death benefit if care is never used. This structure ensures that your premiums are not lost, no matter what happens.
3. Hybrid Policies
These insurance products combine life insurance with long-term care features. They allow the policyholder to
access a % of the death benefit while still alive to pay for caregiving services—such as in-home care, assistance with daily activities, or transportation to appointments. Hybrid policies offer flexibility and peace of mind.
4. Annuities with Long-Term Care Ride
Annuities have significantly improved in recent years. Today, certain annuities can
double your monthly income for a set period if you experience a qualifying LTC event. For example, if you're receiving $6,000 per month in retirement income and meet the criteria, your income could increase to $12,000 per month for a period of time to help cover care costs.
Be Proactive, Not Reactive
These are just a few of the tools available to help you plan ahead for the high costs of healthcare and caregiving later in life. The key is to
start planning early—before a crisis hits. By doing so, you protect not just your savings, but also your independence and the well-being of those you love.
If you haven’t yet talked about LTC planning with your family or financial advisor, now is the time. Because when it comes to long-term care,
it’s not just about protecting assets—it’s about preserving dignity, choice, and peace of mind.