The Perils of Government Over Spending

Karl Van Reusen • October 15, 2023

Nearly all adults have experience with borrowing money. In most cases, we borrow money in order to purchase something we might not otherwise afford. The ability to finance major purchases over a long period of time is the key factor in understanding how our lives are improved by borrowing money. We borrow money from an intermediary, normally known as a bank or credit union. The financial intermediary loans money and accepts the risk of default. Since the lender bears the risk, financial intermediaries have a risk mitigation process known as underwriting. When an individual wants to borrow money, they fill out an application and begin the underwriting process. Basically stated, the underwriting process helps reduce the risk of default by identifying risks that might lead to default. If too many risks are identified, the application is denied. By completing this process properly, financial intermediaries ensure they remain solvent, thus allowing them to lend money to future borrowers.


Governments are ultimately no different than the average consumer, when it comes to borrowing money. The annual budget of any country quite often exceeds the amount of money collected in taxes each year. Just like individual borrowers, governments the world over will borrow funds to finance major purchases or programs. However, one major difference exists. Governments do not borrow money from financial intermediaries but instead, they borrow from current and future taxpayers. Governments will sell sovereign bonds in order to raise money to fund the budget or to pay existing debt. Since there is no intermediary, there is no underwriting process, which as we remember, is a process of mitigating the risk of default. This begs the question, why do we allow the same people spending the money to be the ones to decide if they can borrow more money? Can you imagine the financial chaos that would ensue if we allowed everyone to simply decide for themselves if they could borrow more money? Without the underwriting process, there would be mass default and eventual economic collapse. So how can we ensure governments are borrowing and spending our money wisely, that our elected officials are making prudent decisions and that politicians are not passing on massive debt to future generations?


The simple answer is pay attention and don’t assume all politicians are making good decisions. Fitch is one of three credit rating agencies that assign a credit rating to the United States. In August 2023, Fitch downgraded the US credit rating from AAA to AA+. This is only the second time in the nation’s history that the US sovereign-debt rating has been downgraded. Fitch Ratings cited repeated fights in the US Congress over raising the debt ceiling as a reason for the downgrade. However, it is important to note that this downgrade represents a warning to taxpayers about the US government’s medium and long-term fiscal health, rather than an immediate threat to taxpayers and consumers (2023) If Fitch downgraded the US credit rating for the only the second time in US history and issued warnings about the nations medium and long-term future, we should be concerned.


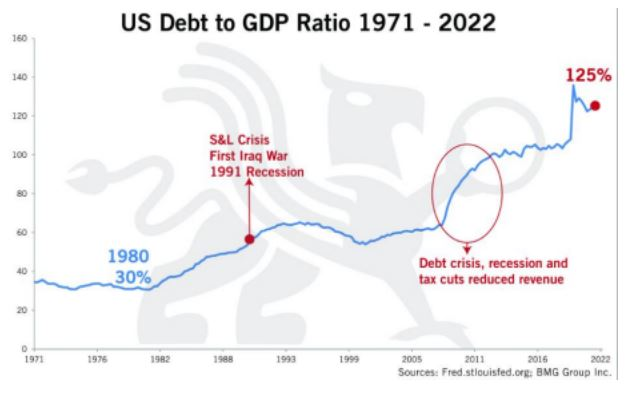
Below is a chart showing the increase in the amount of debt the US creates vs. the amount of GDP. Notice the increases over the past 20 years. The only time in history our government has spent so much as a percentage of GDP was during WWII.


US Debt to GDP Ratio 1971–2022 infographic (The Perils of Government Over Spending article image)


The reason excess spending and radical increases are problematic is due to the increased interest rate payments. Fitch identifies this as a medium to long term problem since future generations will be tasked with payments. The more politicians overspend now, the more debt and interest payments will be passed on. Since we do not collect enough tax dollars to pay the current debt and interest payments, future generations will bear the burden. This burden may come in the form of higher taxes, reduced government programs, a reduced police force, emergency services and military, reduction of government subsidies or grants, reduced social security or other social programs and diminished economic outlook for decades. As a nation, if we want to avoid future economic calamities and ensure our children do not suffer, we must act more responsibly. We must elect those who understand the potential pitfalls of overspending and work cooperatively to remedy the situation.


(2023). Businesstimes.com.sg. https://www.businesstimes.com.sg/wealth/fitchs-us-downgrade principal-agent-problem-modern-finance

Black and gray title slide with
By Eric Boyce • October 16, 2026
Blue title card for B&A Boyce & Associates Wealth Consulting, “Charts & Chat” logo centered.
By Eric Boyce • October 12, 2026
Watch Charts & Chat from October 11, 2026. Eric Boyce, CFA covers the 3.6% GDP estimate, steady jobs, higher rates, rising rents, and the stock bull market.
Black cover for Boyce & Associates Wealth Consulting, “Letters from Eric,” October 2026 outlook on earnings, rates and inflation
By Eric Boyce • October 1, 2026
Eric Boyce, CFA reviews the October 2026 outlook: persistent inflation, higher rates, strong earnings, AI investment, and why diversification matters now.
Three people in a living room discuss aging parents, finances, and peace of mind.
By Kelly Griggs • October 1, 2026
Kelly Griggs, WMS™, CRPC™ explains how to plan for aging parents' care and finances, start the conversation, and protect your family's peace of mind.
Blue title card with B&A Boyce & Associates Wealth Consulting logo and “CHARTS & CHAT” text
By Eric Boyce • September 28, 2026
Watch Charts & Chat from September 27, 2026 with Boyce & Associates. Review the bond sell-off, rising yields, deficits, and AI spending risks today.
People typing on a laptop with text: “Portfolio Management Services Texas: How It Should Work”
By Boyce & Associates • September 28, 2026
See what portfolio management services Texas HNW families choose should include: disciplined allocation, rebalancing, and risk-adjusted design.
By Eric Boyce • September 21, 2026
Explore the latest market and economic insights from Boyce & Associates, covering energy, interest rates, inflation, retail sales, and earnings trends.
Calculator with chart graphics and the text “What is risk-adjusted investment management?”
By Boyce & Associates • September 16, 2026
Learn what risk-adjusted investment management means and how it helps guide portfolio decisions for business owners and high-net-worth families.
Blue logo for B&A Boyce & Associates Wealth Consulting with “Charts & Chat” text
By Eric Boyce • September 15, 2026
Watch Charts & Chat from September 13, 2026 with Boyce & Associates. Review market trends, charts, and insights to support informed decisions.
Financial services graphic with hand, charts, and title: Fiduciary investment management services: what is included
By Boyce & Associates • September 9, 2026
Learn what fiduciary investment management services include, how they differ from a brokerage account, and who benefits most from this approach.
Show More